
If you served in the military, you may be eligible for a home loan benefit. A VA-backed loan is made by a private lender, and the U.S. Department of Veterans Affairs (VA) guarantees part of it. That guaranty protects the lender, which is why these loans can carry features other loans do not. This guide explains the basics, plus a few Texas-specific programs worth knowing about.
Who may be eligible
Eligibility depends on your service history and duty status. VA’s minimum service requirements vary by era, and there are separate rules for service members, National Guard, and Reserve. You can see the full list on VA’s eligibility page. A few key points:
You may qualify based on length of service, or under certain exceptions, such as discharge for a service-connected disability.
An honorable discharge, bad conduct, or dishonorable discharge may limit eligibility, but VA says you can apply and they will review your records.
Surviving spouses may qualify in some situations, such as receiving Dependency and Indemnity Compensation (D.I.C.) or being the spouse of a service member who is missing in action or a prisoner of war.
You must also meet the credit, income, and occupancy requirements set by both the VA and your lender. You must plan to live in the home you buy.
The Certificate of Eligibility (COE)
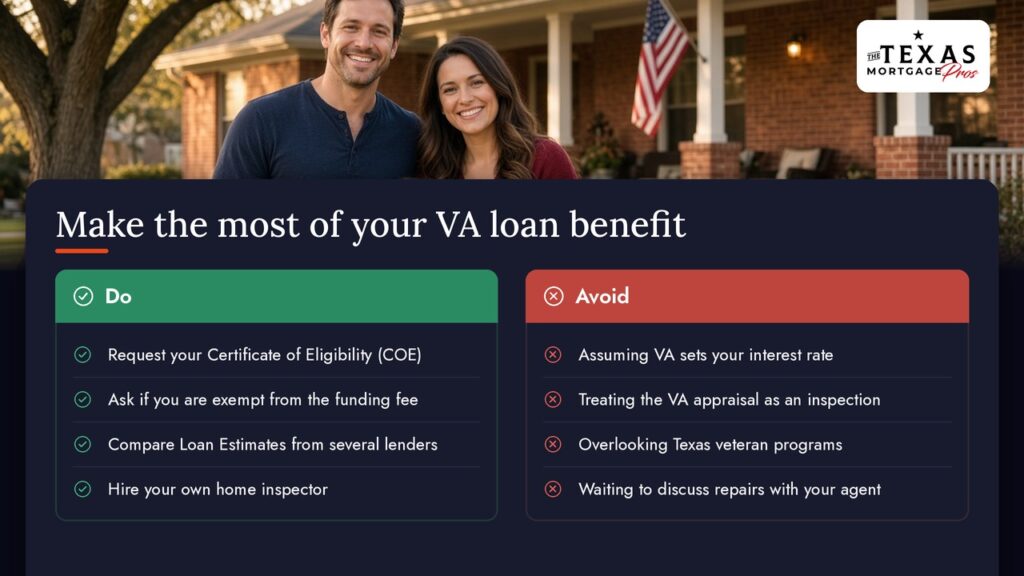
A Certificate of Eligibility shows your lender that you qualify for the benefit. You can request it online through VA, ask your lender to request it for you, or apply by mail. Veterans generally need a copy of their discharge papers (DD214), and service members need a statement of service. VA’s COE page lists what to gather for your situation.
What makes VA loans different
-
Down payment
VA says its guaranty allows most Veterans to buy a home with no down payment, as long as the sales price is not higher than the home’s appraised value. Your lender may still require one in some cases, for example, based on your remaining entitlement or the lender’s own standards. Ask each lender what applies to you.
-
No monthly mortgage insurance
VA-backed loans do not require private mortgage insurance (PMI) or FHA-style mortgage insurance premiums. Instead, most borrowers pay a one-time VA funding fee.
-
The VA funding fee
It is a one-time charge that you can pay at closing or finance into your loan.
The amount depends on the type of loan, the loan amount, and other factors, such as whether this is your first time using the benefit. See VA’s funding fee page for the current charts.
Some borrowers are exempt. Examples VA lists include Veterans receiving VA compensation for a service-connected disability, surviving spouses receiving D.I.C., and certain others.
In some cases, VA may refund the fee if you are later awarded retroactive disability compensation.
-
Credit and income
VA says it does not set a minimum credit score, but many lenders do. Your lender will review your credit, income, debts, and assets. See our guides on buying with a low credit score and how much house you can afford in Texas.
-
Interest rate and fees
VA does not set your interest rate, discount points, or most closing costs. Your lender determines those, and they can vary from lender to lender, so compare Loan Estimates.
The VA appraisal and property requirements
Your lender will order a VA appraisal. The appraiser estimates the home’s value, and the property must meet VA’s Minimum Property Requirements, which are meant to ensure the home is safe, structurally sound, and sanitary. If repairs are required, they will be listed on the Notice of Value. A VA appraisal is not a home inspection, so consider hiring your own inspector. In Texas, VA’s local requirements require wood-destroying insect information in the appraisal. Talk with your agent early about how repair requests are handled in your contract.
Closing costs and seller-paid costs
You and the seller can negotiate who pays many closing costs, and VA allows sellers or builders to offer credits. VA limits certain seller concessions, so ask your lender how this works for your purchase. On a VA purchase loan, only the funding fee can be financed. Other costs are paid at closing.
-
Entitlement and using your benefit again
VA calls the guaranty amount your “entitlement,” and it appears on your COE. VA does not limit how much you can borrow when you have full entitlement, but your lender still decides how large a loan you qualify for. You may be able to restore entitlement or use the benefit again, for example, if you sell a home and repay the loan. VA’s entitlement page explains the details, and a loan officer can help you understand your COE.
Refinancing a VA loan
If you already have a VA-backed loan, an Interest Rate Reduction Refinance Loan (IRRRL) is VA’s streamlined refinance option. VA also has a cash-out refinance option. Read our guide on when refinancing makes sense and when it doesn’t, including the Texas rules for cash-out loans.
Texas Programs for Veterans
-
Texas Veterans Land Board (VLB) home loans
The VLB’s Veterans Housing Assistance Program is a state program administered through the Texas General Land Office (GLO). Eligible Texas veterans and military members may use it to buy a primary residence in Texas. Key points from the GLO:
You must be a Texas resident and meet service and discharge criteria. Surviving spouses of certain veterans may qualify.
The home must be your primary residence in Texas. You must occupy it within 60 days of closing and keep it as your primary residence for at least three years.
The program does not refinance existing loans and cannot be used for down payment assistance.
VLB interest rates and discounts are subject to change at any time. All VLB loans are subject to credit approval.
VLB loans are offered through participating lenders. See the GLO’s home loan page for current requirements, and ask your loan officer whether VLB financing is available for your situation.
-
TSAHC Homes for Texas Heroes
The Texas State Affordable Housing Corporation’s Homes for Texas Heroes program is for people in certain public service roles, including veterans and active-duty military. It may be used with certain loan types. Rules and limits apply, so see our guide to first-time homebuyer programs in Texas.
-
Property tax exemptions for disabled veterans
The Texas Comptroller describes property tax exemptions for veterans with service-connected disabilities:
-
-
- 100 percent disabled veterans. A veteran awarded 100 percent disability compensation by the VA and rated 100 percent disabled or individually unemployable is entitled to an exemption of the total appraised value of the veteran’s residence homestead.
- Surviving spouses may qualify if they have not remarried and the property was and remains their residence homestead.
- Partial exemptions. Veterans with other disability ratings may qualify for a partial exemption on one property they own, with the amount varying by rating.
-
You apply through the county appraisal district, not the state, and a VA determination is required. Our guide to Texas property taxes and your monthly mortgage payment covers how exemptions, appraisal notices, and escrow work. If you expect an exemption, tell your loan officer so you can discuss how taxes will be estimated.
Questions to Ask a Lender
- Do you have experience with VA loans, and will you request my COE?
- Do I need a down payment based on my entitlement and your standards?
- Am I exempt from the funding fee?
- What are the total closing costs, and who can pay them?
- Do you work with VLB financing?
Frequently asked questions
Does VA set my interest rate?
No. According to VA, your lender determines the interest rate, discount points, and other closing costs.
Can I use a VA loan more than once?
Often yes, but it depends on your remaining entitlement and whether you have restored it. Check your COE and ask your lender.
Can a surviving spouse use the VA loan benefit?
Some surviving spouses qualify, depending on their situation. See VA’s eligibility page and ask your lender to help request a COE.
Can I use a VA loan for a condo or a multi-unit home?
VA says you can use a VA-backed purchase loan for a single-family home or a condo in a VA-approved project, up to four units. You must plan to live in the home.
Talk with a local loan officer
A loan officer at The Texas Mortgage Pros can review your situation, explain how a VA-backed loan and Texas programs may fit your needs, and answer your questions. You can start a pre-qualification or call (877) 280-4833.
Official sources
- VA: Eligibility for VA home loan programs
- VA: How to request a Certificate of Eligibility
- VA: Purchase loan
- VA: Funding fee and closing costs
- VA: Entitlement and limits
- VA: Local appraisal requirements
- Texas General Land Office: Veterans Land Board home loans
- Texas Comptroller: Disabled veteran exemptions and 100 percent disabled veteran exemption
- TSAHC down payment assistance
The Texas Mortgage Pros, NMLS #2665861. This article is for general information only. It is not a commitment to lend or extend credit, and it is not legal, tax, or financial advice. VA program rules, Texas programs, and property tax exemptions are subject to change without notice. All loans are subject to credit approval and other restrictions. The Texas Mortgage Pros is not affiliated with or endorsed by the U.S. Department of Veterans Affairs, the Texas Veterans Land Board or Texas General Land Office, the Texas Comptroller, TSAHC, HUD, FHA, USDA, or any government agency, and this is not a government document. Last verified October 2, 2026.
Equal Housing Opportunity. We do business in accordance with federal fair lending laws.
